How can fintech brands acquire customers more efficiently?
- What does it cost to acquire a customer who actually transacts?
- Where should fintech UX design start?
- When is fintech loyalty software worth the investment?
- How do you choose a digital agency for a fintech product?
Imagine signing up for a digital wallet that promises cashback on your first payment. You verify your identity, add funds and reach checkout. Does this purchase qualify? When will the cashback land? You reach for your usual card. The campaign has delivered a signup. The wallet has yet to process a payment.
For a fintech business, improving acquisition efficiency starts with defining what a newly acquired customer came to do. For a wallet, it might be paying for a purchase. For a remittance service, it might be getting money to its recipient. For a merchant, it might be collecting a first payment. Fintech UX design helps teams identify what gets in the way of that outcome. Loyalty software becomes relevant when there is a good reason for customers to come back.
What does it cost to acquire a customer who actually transacts?
Suppose a campaign spends £12,000 on media and delivers 1,200 signups. Of those customers, 300 make a first payment within seven days. That puts media spend at £10 per signup and £40 per first-time payer. If 400 customers make a payment on the same budget and signup volume, spend per first-time payer falls to £30. This is a media efficiency measure. A fully loaded customer acquisition cost also includes the other sales and marketing costs attributable to acquisition.
Rank channels by both figures. A campaign that delivers inexpensive signups can be an expensive way to find merchants who collect a payment. Give every signup cohort the same time to activate. Comparing Monday’s signups with Friday’s signups on Friday evening systematically understates the newer group’s performance. Amplitude’s guide to acquisition and activation metrics
Where should fintech UX design start?
Consider the 900 wallet customers who signed up without paying. A customer who cannot complete an identity check needs different help from someone who has funded their wallet and backed out at checkout.
| Observed behaviour | Question to investigate | Design change to test |
|---|---|---|
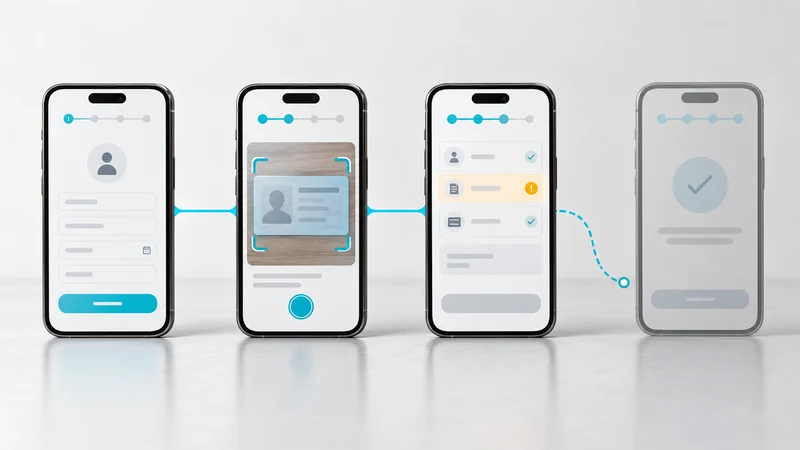
| Customers start identity verification and leave | Did they have the document ready? Could they recover from a failed scan? | Show document requirements upfront and let people retake an unreadable image in place. |
| Customers leave the payment review screen | Did the total, fee or cashback eligibility come as a surprise? | Show the amount due, any fee and the reward for this purchase before confirmation. |
| Customers submit a payment again | Could they tell whether their first attempt went through? | Distinguish pending, completed and failed payments, with a clear next step for each. |
A funnel can point you towards the right screen. A usability session can reveal what the customer still needs to know. Ask someone at checkout, “How much will leave your wallet today, and how much will you get back?” If they need to leave checkout and search the offer terms to answer, you have identified a specific gap in the payment review.
Choose the outcome before testing the change. For a revised review screen, track the share of new customers who see it and complete their first payment. Monitor duplicate attempts and payment-related support requests alongside completion.
When is fintech loyalty software worth the investment?
If first payments are healthy but repeat usage is low, look for the next occasion on which customers might reasonably choose your product. A commuter who buys coffee at the same shop each week may value credit towards the next eligible purchase. For a product people use once a year, a 30-day repeat target tells a different story.
Ask prospective fintech loyalty software providers to demonstrate a purchase from start to finish, including a refund. Can customers tell whether they qualify before paying? What do they see while the reward is pending? If the merchant refunds the purchase, can a support agent explain the balance adjustment? A demo built around one customer’s transaction will tell you more about the experience than a list of campaign features.
To estimate the return, randomly assign eligible new customers to an offer group and a holdout group. After 30 days, compare repeat payment rates and contribution per eligible customer, accounting for transaction revenue, variable processing costs and rewards. If the offer generates more transactions but less contribution per customer, check whether later usage covers the difference before rolling it out.
How do you choose a digital agency for a fintech product?
Start by telling potential partners where acquisition breaks down. If qualified customers rarely reach the product, ask about audience selection and media buying. If qualified applicants arrive but fail to transact, ask a specialist fintech UX studio to walk you through a comparable journey.
Three questions make a portfolio review more revealing. Where did customers get stuck? How did the team find out? Which design decision changed as a result? For corporate banking, add a scenario. When one person creates a payment and another authorises it, how does each know who needs to act next?
At VOYA, our work on Hayat Finans’s corporate digital banking platform included user interviews, flow design, prototyping and revisions informed by feedback. The case study shows how the team moved from research into interface design. Explore the Hayat Finans digital banking project
To write your first brief, choose one acquisition channel and one transaction. Take last month’s cohort and count how many customers completed that transaction, how many came back and where the largest drop occurred. You can then give your team a question it can investigate, such as “Why do customers fund their wallet and still use another card at checkout?”


Explore All Blogs
Ready to talk
about your project?
Do you have a clear vision regarding the ideas, goals, requirements, and desired outcomes for your project? Let's take the first step together by setting up a meeting to bring all of these to life.