AI Transformation in Fintech: A Practical Guide to Strategy and User Experience
- Why does AI matter in financial services?
- Which AI approach fits which fintech problem?
- Key use cases for AI in fintech
- 1. Fraud detection and transaction security
- 2. Credit assessment and decision support
- 3. Customer support and employee assistants
- 4. Personal finance and cash flow experiences
- 5. Wealth management and adviser productivity
- 6. Document processing and operational review
- How to get started with AI transformation in fintech
- 1. Define the problem and establish a baseline
- 2. Prioritize use cases by value and risk
- 3. Design the data flows and permissions
- 4. Decide where human oversight is required
- 5. Validate against realistic scenarios
- 6. Start with a controlled pilot and expand based on evidence
- How should user experience be designed for AI-powered fintech products?
- Make the system’s actions clear
- Explain uncertainty in specific terms
- Provide access to sources and ways to correct errors
- Design an alternative path
- Which metrics should measure success?
- The main risks when scaling AI
- VOYA’s approach: Integrating AI into how a product works
- Frequently asked questions
- What is AI transformation in fintech?
- Where can fintech companies use AI?
- Do we need to build our own model to get started?
- Can AI fully automate financial transactions?
- How should we choose our first AI project?
- Sources
A customer wants to understand why a money transfer failed. An operations specialist needs to bring together data from several systems to investigate a suspicious transaction. A financial adviser reviews documents and previous notes before a client meeting.
Each task involves a gap between finding information and taking the right action. Much of the value AI can bring to fintech products lies in closing that gap.
AI transformation in fintech means integrating artificial intelligence into products, decision processes, and operations to redesign how financial services are delivered. It requires a coordinated approach to data infrastructure, team workflows, user experience, and accountability.
When an implementation works well, customers can complete tasks more easily, employees can make better-informed decisions, and the business can measure the benefit. The starting question is straightforward: Which problem can AI solve better than the methods already available?
Why does AI matter in financial services?
Financial services combine large volumes of data, repetitive operations, and complex decisions. Together, these create a broad range of opportunities for AI.
In the Bank of England and Financial Conduct Authority’s 2024 survey, 75% of responding firms reported using AI, compared with 58% in the 2022 survey. These figures describe the UK survey respondents; they should not be treated as an adoption rate for the global fintech industry. [1]
For product teams, the potential value falls into three areas:
- Decision support: Making patterns in large datasets easier to identify.
- Operational efficiency: Reducing the work involved in finding information, reviewing documents, and preparing materials.
- User experience: Presenting financial information in a way that fits the person’s needs and the task at hand.
Launching an AI feature does not, by itself, establish that these benefits have been achieved. An assistant whose answers constantly need correcting can create more work. A system that flags too many legitimate transactions as suspicious can make payments harder to complete.
AI transformation in fintech should therefore be managed as a product development process that measures both value and the cost of errors.
Which AI approach fits which fintech problem?
Machine learning, generative AI, and AI agents serve different purposes. Understanding those differences helps teams define the scope before choosing technology.
| Approach | Core function | Fintech example |
|---|---|---|
| Machine learning | Identify patterns in data to generate predictions or classifications | Transaction risk scoring, cash flow forecasting |
| Generative AI | Process text and documents and produce explanations or drafts | Drafting support responses, summarizing documents |
| AI agents | Use defined tools to carry out tasks with multiple steps | Gathering data for a request, running checks, and preparing a transaction draft |
| Rule-based automation | Apply predetermined conditions | Limit checks, mandatory approvals, transaction restrictions |
A product may combine several approaches. Machine learning could score the risk of a transaction, a rules engine could determine the required control, and generative AI could summarize the findings for an operations specialist.
A model’s ability to explain an action does not mean it needs permission to execute it. In workflows that move money, this distinction is a fundamental product architecture decision.
Key use cases for AI in fintech
1. Fraud detection and transaction security
AI can help identify suspicious activity by analyzing transaction patterns, account behavior, and other risk signals. Itransition’s fintech overview also identifies fraud detection and credit assessment as major application areas. [2]
From a product perspective, the objective should extend beyond detecting more suspicious transactions. Teams also need to measure how often legitimate activity is unnecessarily blocked.
For example, a payments app might request additional verification for a transaction that appears risky. The user needs to understand what to do, be able to complete verification, and have access to support when necessary.
Success metrics should cover fraud losses, false positives, payment completion, and the workload required to review alerts.
2. Credit assessment and decision support
AI-assisted credit assessment can help teams analyze different data sources together and review applications more quickly.
However, more data does not automatically produce fairer or more accurate decisions. The Financial Stability Board warns that poor data quality and inadequate data governance can amplify existing biases. [3]
Product teams should assess:
- Whether the data is appropriate for the decision.
- How the model performs across different customer groups.
- Whether decision reasons are understandable.
- How incorrect or missing information can be corrected.
- When a case should move to human review.
The explanation shown to the user must be consistent with the evidence behind the actual decision. Persuasive text generated afterward by a language model cannot substitute for verified decision reasons.
3. Customer support and employee assistants
Generative AI can classify support requests, summarize conversations, and prepare draft responses for employees.
Intuit’s fintech overview identifies customer experience, personalization, and operational automation as important AI application areas. [4]
For a fintech product, the answer needs to reflect the customer’s actual circumstances. A system answering “When will my refund arrive?” should be able to use current transaction information within its access permissions, rather than simply provide a generic estimate.
An employee support assistant can be a useful starting point: AI retrieves the relevant records and prepares a draft, which a specialist reviews before sending it to the customer. This preserves a review step while generating evidence from real use.
Response time is only one measure of performance. First-contact resolution, repeat contacts, incorrect information, and escalation to human support should also be tracked.
4. Personal finance and cash flow experiences
Expense categorization, visibility into upcoming payments, and cash flow forecasting are areas where AI can make financial information more useful.
For example, a financial app for small businesses could highlight a potential future cash shortfall based on expected receipts and scheduled payments.
The quality of the experience depends on how the forecast is presented:
- Which data was used?
- When was it last updated?
- What assumptions were made?
- Can the user change those assumptions?
- What happens when actual results differ from the forecast?
Financial forecasts should not be presented as certain outcomes. Users need to distinguish between a current balance, a calculated scenario, and a model-generated prediction.
5. Wealth management and adviser productivity
In wealth management, AI can support research access, meeting preparation, and client communication. The relevant CFA Institute webinar page highlights personalization, the combination of human and machine capabilities, data privacy, and cybersecurity. [5]
Morgan Stanley’s Debrief tool provides a concrete example. According to the company’s June 2024 announcement, the tool creates meeting notes and action items with client consent and prepares an email draft that the adviser can edit and send. [6]
The product lesson is that AI is embedded in a specific workflow. The meeting, summary, follow-up actions, and client communication are connected, while the adviser continues to review the output.
6. Document processing and operational review
Many fintech operations tasks involve extracting information from documents and comparing records.
An AI-assisted workflow can identify missing fields, flag inconsistencies between documents, and prepare a review summary for a specialist.
Showing the relevant part of the source document alongside the summary helps the specialist verify the extracted information. Performance measures should include missed inconsistencies and the need for corrections, as well as processing time.
How to get started with AI transformation in fintech
The roadmap below is a proposed framework for product teams defining their initial scope. Timing and implementation will depend on data readiness, integrations, and the risk associated with the use case.
1. Define the problem and establish a baseline
“Let’s build an AI assistant” is a solution idea. The first step is to explain the need it addresses.
For example:
Support specialists gather information from several screens when reviewing transaction disputes. Our goal is to reduce the preparation time needed to reach the correct outcome.
This statement identifies the user, the workflow, and the result to measure.
Before development begins, measure current handling time, error rates, request volume, and operating costs. Without a baseline, it becomes harder to assess how much of any improvement can be attributed to AI.
2. Prioritize use cases by value and risk
Evaluate each scenario using the following questions:
| Criterion | Evaluation question |
|---|---|
| User value | What difficulty does it reduce? |
| Business value | Which measurable outcome does it improve? |
| Data readiness | Is the required data accessible and of sufficient quality? |
| Error impact | What could an incorrect output cost the user or the business? |
| Verifiability | Can the output be checked for accuracy? |
| Implementation effort | Which systems and teams need to change? |
For an initial pilot, it is useful to choose a bounded process with verifiable outputs and manageable errors. An internal document assistant and an automated credit decision system, for example, require different levels of evaluation.
3. Design the data flows and permissions
Clarify the data flow before selecting a model.
Define where information comes from, who can access it, how current it is, and what it can be used for.
Customer data that an employee cannot otherwise access must not become available through an AI assistant. This control should be enforced through the application’s data access and authorization mechanisms, rather than left solely to instructions given to the model.
4. Decide where human oversight is required
Human oversight involves more than adding an approval button.
The person approving an action needs to see the supporting evidence, recognize errors, and stop the process when necessary. A workflow in which people routinely approve every suggestion because of workload pressure does not provide effective oversight.
Each task can be assigned an explicit level of authority:
- Present information.
- Prepare a recommendation or draft.
- Execute an action after approval.
- Perform an action automatically within defined limits.
These levels should reflect the potential cost of an error.
5. Validate against realistic scenarios
Testing should cover more than straightforward examples. Missing data, outdated documents, conflicting records, unauthorized requests, and service outages all need attention.
Generative AI applications also require evaluation of fabricated information and security risks. NIST’s Generative AI Profile provides a voluntary framework that organizations can use to identify and assess these risks. [7]
Write acceptance criteria before the pilot begins: Which errors are unacceptable? When is human review required? What result should trigger a pause in use?
6. Start with a controlled pilot and expand based on evidence
Run the pilot with a limited group of users and a defined scope. Record employee corrections, points where users fail to complete a task, and situations in which the system cannot provide an answer.
Expansion decisions should consider quality, cost, and risk indicators alongside usage.
When the model, data source, or workflow changes, reassess whether previous test results still apply.
How should user experience be designed for AI-powered fintech products?
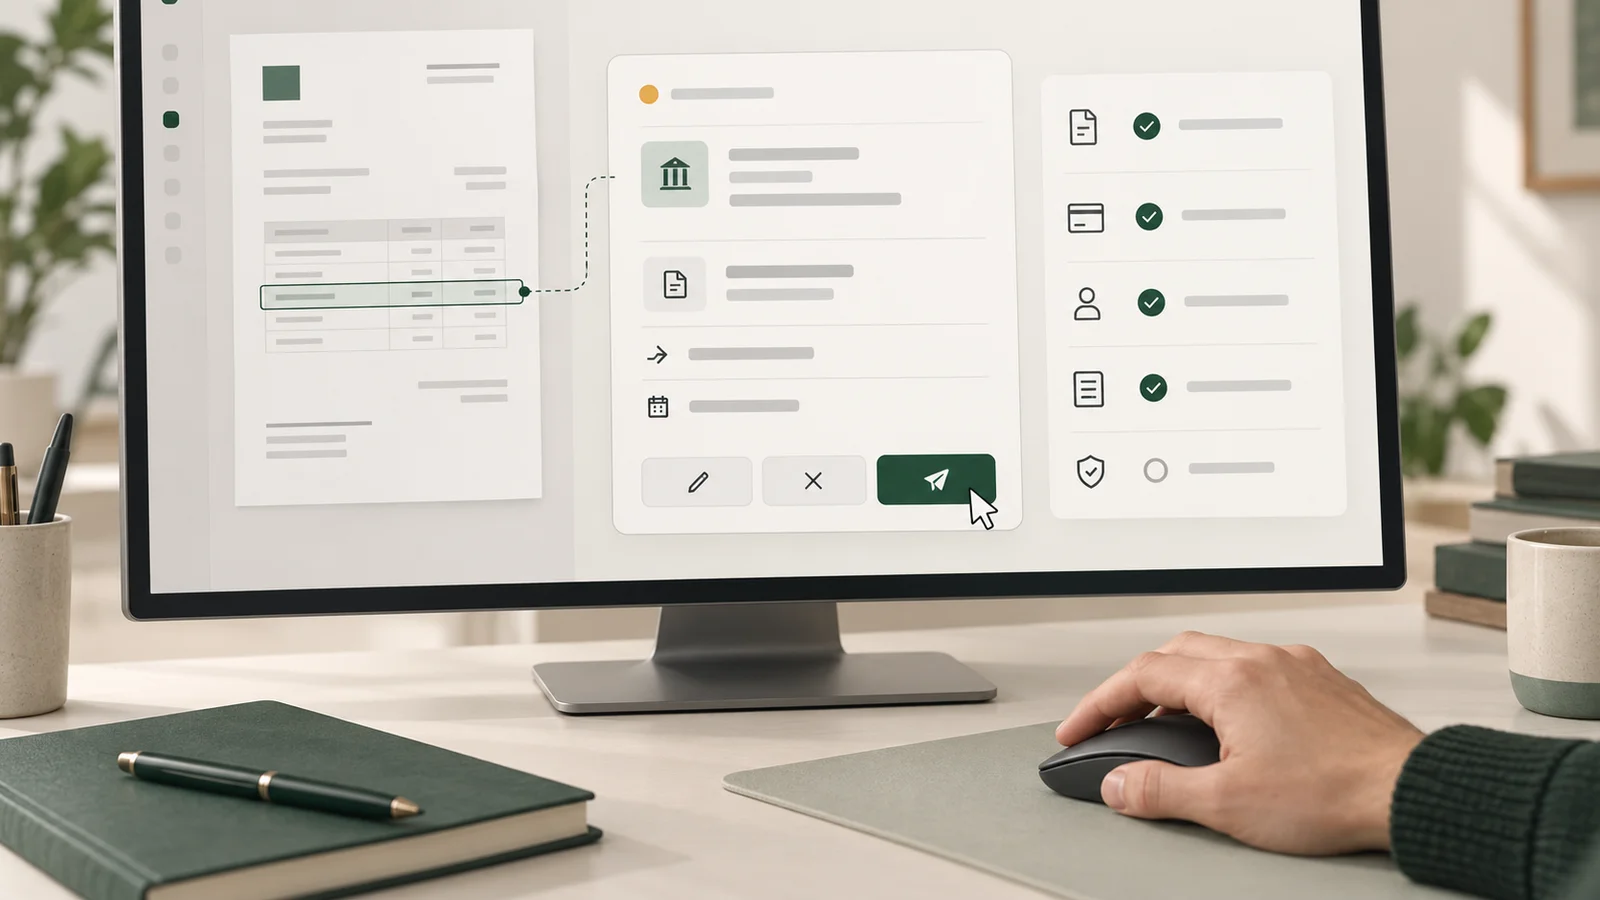
Helping users interpret AI output correctly is part of the product’s functionality.
Make the system’s actions clear
Users should be able to tell whether they are viewing a recommendation, reviewing a transaction draft, or looking at the result of a completed action.
The difference between “Your payment is ready” and “Your payment has been sent” has direct financial consequences.
Explain uncertainty in specific terms
A general warning that “AI can make mistakes” offers limited help when someone needs to make a decision.
A statement such as “This forecast includes transactions from the past three months; payments that have not yet been recorded are excluded” is more useful. It explains the boundaries of the result.
Provide access to sources and ways to correct errors
When presenting a document summary, transaction explanation, or cash flow forecast, provide access to the underlying information. Appropriate workflows should allow incorrect classifications and missing data to be corrected.
Design an alternative path
Users need a way to continue when AI cannot help. Manual search, a standard transaction screen, or human support should be part of the product experience.
Trust grows when users understand the system and can intervene when necessary. It should not depend on the impression that AI is always right.
Which metrics should measure success?
AI transformation can be evaluated across four dimensions:
| Dimension | Example metrics |
|---|---|
| User experience | Task completion, abandonment, repeat contacts |
| Operations | Handling time, manual review workload, rework |
| Quality and risk | Incorrect outputs, false positives, unauthorized access attempts |
| Economic value | Total cost per successful task, realized capacity gains |
Cost calculations should include integration, monitoring, human review, and error correction alongside model usage.
Time saved should also be distinguished from financial savings. Completing a task more quickly can create additional capacity; whether that capacity translates into lower costs or additional revenue needs to be measured separately.
The main risks when scaling AI
As AI adoption expands, organizational dependencies become increasingly important alongside model performance.
The FSB’s 2024 report identifies third-party dependencies, cyber risks, model risk, and data governance as important issues for financial stability. [8]
For product and technology teams, this means defining alternative workflows for service outages, change controls, and accountable teams before expanding deployment.
The FSB’s June 2026 consultation report also proposes practices for organization-wide AI governance and lifecycle management. It is a consultation document and should not be treated as binding regulation. [3]
Each organization should assess the requirements relevant to its activities and markets for each use case.
VOYA’s approach: Integrating AI into how a product works
At VOYA, we approach AI product transformation by considering product workflows and user experience together. We start with what users are trying to achieve and where the current experience makes that difficult.
In fintech, this means designing AI’s role, the control users retain, and the expected product impact as connected decisions.
A support assistant needs reliable access to relevant information. A financial dashboard needs to make forecasts understandable. A transaction workflow needs to make the meaning of approval clear. The same technology requires different experience decisions in different product contexts.
VOYA’s AI product transformation approach brings these opportunities together through product strategy and experience design.
The value of AI transformation in fintech becomes visible when users can move forward more easily and make better-informed decisions. A strong starting point is a clearly defined problem, a bounded use case, and a measurable success criterion.
Frequently asked questions
What is AI transformation in fintech?
It is the integration of AI into financial products, operations, and decision processes to improve how services are delivered. It requires a coordinated approach to data, technology, user experience, and governance.
Where can fintech companies use AI?
Major use cases include fraud detection, credit assessment, customer support, document processing, cash flow forecasting, and employee decision support. The right use case depends on the organization’s needs and data readiness.
Do we need to build our own model to get started?
Not for every use case. Existing models and infrastructure may be suitable. The choice should depend on data requirements, quality, cost, latency, control, and integration needs.
Can AI fully automate financial transactions?
Technical capability alone is not enough to make that decision. The level of automation should reflect the action’s impact, whether it can be reversed, applicable requirements, and the organization’s approach to risk.
How should we choose our first AI project?
Choose a recurring, measurable problem with accessible data, verifiable outputs, and manageable error consequences. The pilot should produce evidence that can inform broader deployment.
Sources
- Bank of England and FCA — Artificial intelligence in UK financial services, 2024
- Itransition — AI in fintech: use cases, solutions, trends & implementation challenges
- Financial Stability Board — Sound Practices for Financial Institutions’ Responsible AI Adoption: Consultation Report, June 2026
- Intuit — How AI Is Transforming Financial Technology (Fintech)
- CFA Institute — Technology disruption: How AI and fintech are transforming wealth management
- Morgan Stanley — AI @ Morgan Stanley Debrief announcement, June 2024
- NIST — Artificial Intelligence Risk Management Framework: Generative Artificial Intelligence Profile
- Financial Stability Board — The Financial Stability Implications of Artificial Intelligence, November 2024


Explore All Blogs
Ready to talk
about your project?
Do you have a clear vision regarding the ideas, goals, requirements, and desired outcomes for your project? Let's take the first step together by setting up a meeting to bring all of these to life.